

TL;DR:
- Managing rental taxes in Cape Coral involves reporting all income on Schedule E and claiming all deductible expenses such as mortgage interest, insurance, repairs, and management fees. Advanced strategies like cost segregation and bonus depreciation can significantly reduce tax liability, but require meticulous recordkeeping and professional guidance. Consistent organization and proper documentation are essential to avoid audit issues and maximize tax savings over the long term.
Owning a rental property in Cape Coral sounds like a dream until tax season arrives and you realize you have no idea how to manage rental taxes without leaving money on the table. Most landlords either miss deductions they are legally owed or make filing errors that trigger IRS attention. Neither is fun. The good news is that with the right framework, managing rental income taxes is far less painful than it looks, and the payoff in tax savings can be genuinely substantial. This guide walks you through the basics, the advanced strategies, and the record-keeping habits that keep audits away.
Table of Contents
- Key takeaways
- How to manage rental taxes: the basics you need first
- Advanced strategies that serious investors use
- Recordkeeping that holds up in an audit
- Common filing mistakes and how to avoid them
- My honest take on mastering rental taxes
- Let Home24seven help you stay organized and compliant
- FAQ
Key takeaways
| Point | Details |
|---|---|
| Report all rental income | All rental income goes on Schedule E of your Form 1040, regardless of whether you use a property manager. |
| Claim every deduction | Mortgage interest, insurance, repairs, and management fees are all deductible and reduce your taxable rental income. |
| Use depreciation every year | Skipping depreciation is a costly mistake because the IRS taxes the recapture anyway when you sell. |
| Advanced strategies add up | Cost segregation and bonus depreciation can move large deductions into Year One, dramatically cutting your tax bill. |
| Keep meticulous records | Organized receipts, logs, and bank statements protect you in an audit and support every deduction you claim. |
How to manage rental taxes: the basics you need first
Before you can start applying smart strategies, you need a solid grip on how rental income is taxed and which expenses knock down that taxable number. Think of this as your foundation. Without it, the advanced stuff is just noise.
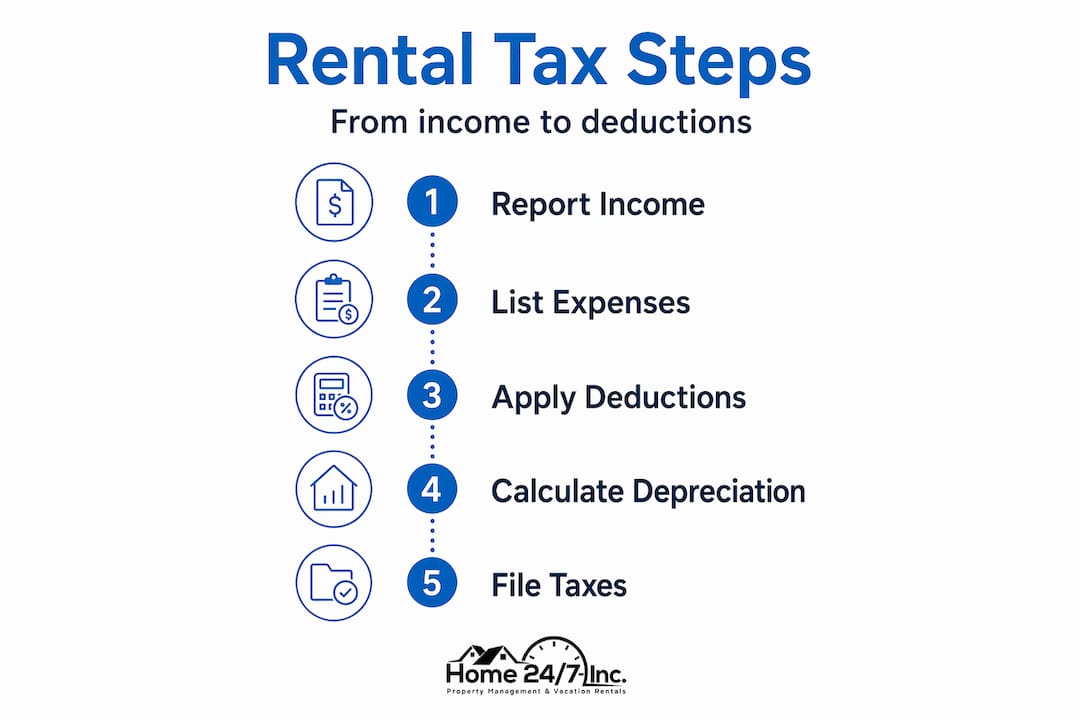
Rental income is reported on Schedule E of your Form 1040. This includes rent payments, late fees, and any services tenants provide in lieu of rent. The IRS is not particularly forgiving about what counts as income, so report it all. The silver lining is that rental taxes are fully deductible on Schedule E without the SALT cap limitations that hit your primary residence.
The deductions that reduce your taxable income
Here is where most landlords leave real money on the table. These expenses are all deductible:
- Mortgage interest on your rental property loan
- Property taxes assessed on the rental
- Insurance premiums including landlord, flood, and liability policies
- Repairs and maintenance like fixing a leaky faucet or patching drywall
- Property management fees, which typically run 8 to 12% of rent collected
- Travel expenses to manage the property, including airfare, hotel stays, and 50% of meals when your trip is primarily for rental business
- Cleaning services for your rental unit, including professional turnovers between guests
One distinction matters a lot here: repairs versus capital improvements. A repair fixes something that is broken and is immediately deductible. A capital improvement, like replacing the entire roof or installing a new HVAC system, adds value and must be depreciated over time. Mixing these up is one of the most common audit triggers, so it pays to understand the line.
Depreciation: the deduction most landlords underuse
Depreciation lets you deduct the cost of the building itself (not the land) over 27.5 years. On a $300,000 structure, that is roughly $10,900 per year off your taxable income without spending another dime. Here is the part that catches people off guard: if you skip claiming depreciation, the IRS still charges you for depreciation recapture at up to 25% when you sell. You pay the tax whether you took the deduction or not. Always claim it.
Pro Tip: The $2,500 de minimis safe harbor rule lets you expense items immediately instead of capitalizing them, as long as each item costs $2,500 or less. Replacing several cabinet handles or a small appliance? Deduct it this year, no depreciation schedule needed.
Advanced strategies that serious investors use
Once you have the basics covered, there are several more powerful strategies that separate investors who break even on taxes from those who build real wealth through tax efficiency.
-
Cost segregation. This is a professional study that breaks your property into its components, like appliances, flooring, landscaping, and fixtures, and assigns shorter depreciation lives to each. A well-executed study can identify 25% of property basis eligible for accelerated deductions. On a $600,000 property, that could mean $150,000 moving into Year One deductions.
-
Bonus depreciation. The One Big Beautiful Bill Act restored 100% bonus depreciation for qualified property starting in 2025. Pair this with cost segregation, and you can create massive front-loaded deductions in the first year of ownership.
-
Active participation rules. If your adjusted gross income is under $100,000, you can deduct up to $25,000 in rental losses against your regular income. This phases out by $150,000. Active participation does not mean you are swinging a hammer. It means you make key decisions: approving tenants, setting rent, and authorizing major repairs.
-
Short-term rental strategy. If your average guest stay is seven days or fewer, your rental is not classified as a passive activity by default. Combined with material participation in the property, this opens the door to deducting losses against active income without the passive loss limitations.
One underused piece of tax strategy: the marital loophole. If one spouse qualifies as a real estate professional by spending more than 750 hours per year in real estate activities, the couple can deduct real estate losses against their full active income. It requires meticulous time logs, but for the right household, the savings can be significant.
A common misconception is that hiring a property manager disqualifies you from active or material participation. Not true. As long as you retain authority over decisions like tenant approval and major repairs, you maintain your participation status. Delegating the day-to-day work is not the same as stepping away from ownership authority. Learn more about how management agreements affect participation before you assume you have lost this benefit.
Recordkeeping that holds up in an audit
Good tax strategy without good records is like a beautiful house with no foundation. The IRS requires documentary evidence for all rental income and expenses, and that means actual receipts, not just bank statements.
Here is what you should be keeping:
- Receipts and invoices for every repair, maintenance call, and supply purchase
- Bank statements from a dedicated rental account (keep personal and rental finances completely separate)
- Travel logs with dates, mileage, destination, and purpose for every property visit
- Closing documents for purchase and sale, including settlement statements
- 1099 forms from any tenant paying over $600 per year in rent and from any contractor you pay
- Lease agreements and any written communications with tenants
The IRS generally recommends keeping records for at least three years, but for capital improvements, you should hold those documents as long as you own the property and for three years after you sell it. That roof replacement you did in year two affects your depreciation schedule and your capital gains basis for decades.
Pro Tip: Using a dedicated bank account and property management software makes year-end tax prep dramatically simpler. Every transaction is automatically categorized, and your accountant will spend less time sorting receipts and more time finding deductions.
Common filing mistakes and how to avoid them
Even experienced landlords trip over these. Knowing the pitfalls is half the battle.
-
Confusing repairs with improvements. Replacing a broken window is a repair. Replacing all the windows in the house to upgrade efficiency is a capital improvement. The distinction affects whether you deduct it now or over many years. When in doubt, consult your CPA before you categorize it.
-
Skipping depreciation. This is shockingly common, and it is expensive. Not claiming depreciation does not protect you from depreciation recapture tax when you sell. The IRS calculates it as if you took it. Always claim it, every single year.
-
Misunderstanding active participation. Many landlords assume they do not qualify simply because they hired a property manager. If you still make final calls on tenant selection and major expenditures, you likely still qualify for the $25,000 passive loss deduction.
-
Inflating travel deductions. Travel deductions are legitimate but must be documented and primarily for rental business. Mixing a week of vacation into a two-day property visit and deducting the whole trip is an audit magnet. Keep travel logs and be honest about the split.
-
Ignoring state and local tax rules. Florida has no state income tax, which is great news for Cape Coral owners. But short-term rentals face local tourist development taxes and transient rental taxes that vary by county. Check your Florida vacation rental tax obligations to make sure you are fully compliant at every level.
Verifying your rental tax filings for accuracy
Before you hit submit on that return, run through this checklist:
| Item to verify | What to check |
|---|---|
| Income entries | Cross-reference rent received against bank deposits and 1099 forms |
| Expense categories | Confirm repairs vs. improvements are correctly classified |
| Depreciation schedule | Review Form 4562 to verify basis and recovery period |
| Passive loss limits | Check Form 8582 to confirm loss limitations are applied correctly |
| Participation status | Confirm time logs support active or material participation claims |
If your situation involves cost segregation, bonus depreciation, or the short-term rental strategy, work with a CPA who specializes in real estate. The tax code rewards complexity, but only when it is executed correctly.
My honest take on mastering rental taxes
From where I sit, the biggest difference between investors who stress about tax season and those who actually look forward to it is preparation built throughout the year, not a frantic scramble in April.
I have seen landlords walk into audits with shoeboxes of receipts and walk out fine, simply because every deduction had a matching document. I have also seen investors lose thousands of dollars in disallowed deductions because they could not prove a repair was a repair and not an improvement. The records do not lie. The IRS knows it, and now so do you.
The area where I see the most untapped value is cost segregation. Most rental owners assume it is only for large commercial portfolios. But a single vacation rental in Cape Coral, purchased at today’s prices, can yield enough accelerated deductions to meaningfully change your tax bill in Year One. It requires a professional study, and it requires clean documentation, but the return on that investment is often remarkable.
My honest advice: do not try to optimize your rental taxes without a real estate-focused CPA in your corner. The tax code is genuinely complex in this area, and the difference between a good generalist accountant and a specialist is often thousands of dollars.
— Philipp
Let Home24seven help you stay organized and compliant
Managing rental taxes well starts with organized operations, and that is exactly what Home24seven does best for Cape Coral property owners.
Since 2017, we have helped vacation rental owners keep their properties running smoothly and their finances clean. Our property management services include detailed income and expense reporting that makes tax time far less stressful. Our fees are fully deductible as a rental expense, which means professional management practically pays for itself in tax savings. We also work closely with owners on transparent financial reporting so your CPA has everything they need without chasing down statements. Ready to simplify your rental operations and make tax season something you actually feel prepared for? Let’s talk.
FAQ
What forms do I need to file rental taxes?
Report rental income and expenses on Schedule E, attached to your Form 1040. If you claim depreciation, also file Form 4562. If you have passive losses, Form 8582 tracks the limitations.
Can I deduct my property manager’s fees?
Yes. Property management fees, including leasing fees and lease renewals, are fully deductible as ordinary rental expenses on Schedule E.
Does hiring a property manager disqualify me from active participation?
No. As long as you retain decision-making authority over tenant approvals and major expenses, you can still qualify for active participation and the $25,000 passive loss deduction.
What happens if I forget to claim depreciation?
The IRS applies depreciation recapture tax when you sell at up to 25%, regardless of whether you actually claimed the deduction. Always claim depreciation every year to offset the tax you will owe anyway upon sale.
Are short-term rentals taxed differently than long-term rentals?
Yes. Short-term rentals with an average guest stay of seven days or fewer may not be classified as passive activities, which can unlock loss deductions against active income when material participation requirements are met.

