

TL;DR:
- Cape Coral’s short-term rental market is highly unpredictable, with demand fluctuations influenced by weather, construction, and competition. Accurate forecasting combines local market data, comparable property analysis, and scenario testing to manage income uncertainties effectively. Utilizing professional management and building flexible, risk-aware financial models helps investors survive setbacks and maximize their rental profitability.
If you’re eyeing last year’s rental deposit slips and assuming next year will look roughly the same, we hate to break it to you — Cape Coral’s short-term rental market doesn’t play by those rules. A single hurricane season, a stretch of construction on your street, or even a competing property dropping their rates can send your income sliding faster than a pelican spotting a fish. The good news? Forecasting gives you something far more powerful than a hunch. It turns uncertainty into a structured, manageable plan, and once you understand how the numbers actually work, you’ll stop guessing and start strategizing.
Table of Contents
- What is rental income forecasting?
- How forecasting works for short-term rentals
- Building reliable forecasts: Beyond basic formulas
- NOI, cash flow, and using forecasts to make decisions
- Our take: What most Cape Coral investors miss in income forecasting
- Take forecasting further with Cape Coral property experts
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Forecasting beats guesswork | Relying on structured data, not last year’s income, is the key to consistent rental profits. |
| Local comps matter most | Always use Cape Coral-specific market data to set accurate expectations for your property. |
| Model for risk and upside | Run scenarios for low and high years—don’t just calculate a single number. |
| NOI drives smart decisions | Understand how net operating income influences property value and lender choices. |
| Expert help pays off | Professional management and forecasting can yield higher, more reliable rental income. |
What is rental income forecasting?
Now that you understand why relying on past profit is risky, let’s clarify what rental income forecasting actually means and how it’s calculated.
At its core, rental income forecasting is the process of estimating future booking revenue a property will generate, typically by projecting demand (occupancy), pricing (average daily rate, or ADR), and the number of rentable days, then converting that revenue into financial outcomes after accounting for operating costs and vacancy. That’s a mouthful, so let’s break it down into bite-sized pieces.
The main building blocks of a forecast:
- ADR (average daily rate): The average nightly price guests pay for your property.
- Occupancy rate: The percentage of available nights your property is actually booked.
- Available nights: The total number of nights your property is on the market each year.
- Gross rental income: ADR multiplied by total booked nights.
- Operating expenses: Cleaning fees, maintenance, management fees, insurance, utilities, and taxes.
- NOI (net operating income): Gross income minus operating expenses, before mortgage payments.
Here’s a simple example. Imagine you own a 3-bedroom canal home in Cape Coral. You price it at $250 per night, you have 300 available nights per year, and you achieve a 70% occupancy rate. That gives you 210 booked nights at $250, for a gross rental income of $52,500. Subtract $18,000 in operating expenses, and your NOI lands at $34,500. That NOI is the number lenders, buyers, and smart investors care about most.
| Input | Value |
|---|---|
| ADR | $250/night |
| Available nights | 300 |
| Occupancy rate | 70% |
| Booked nights | 210 |
| Gross rental income | $52,500 |
| Operating expenses | $18,000 |
| Net operating income (NOI) | $34,500 |
“A rental income forecast isn’t just about what you hope to earn. It’s a model built on real data, and the gap between modeling and guessing is the gap between a thriving property and an expensive surprise.”
For Cape Coral owners, pairing this formula with Cape Coral rental strategies that reflect local demand patterns makes your forecast significantly more reliable than anything built on national averages alone.
How forecasting works for short-term rentals
With the basics of what forecasting is, let’s unpack the process used by successful short-term rental owners — specifically how comps and market data bring clarity to your Cape Coral investments.
For short-term rentals, forecasting leans heavily on market data and comparable properties — commonly called “comps” — to estimate ADR, occupancy rates, and overall revenue potential. This is similar to how real estate agents use comparable sales to price a home, except here you’re pricing future income instead of a purchase price.
Here’s how the process looks step by step:
- Identify your property type and location. A waterfront 4-bedroom with a pool performs very differently from an inland 2-bedroom studio. Define your category clearly.
- Gather local market data. Use tools and market reports that track ADR and occupancy trends in Cape Coral specifically. Cape Coral market data shows ADR and occupancy benchmarks you can use as starting inputs.
- Select comparable listings. Find 5 to 10 active rentals in Cape Coral that match your property in size, amenities, and location. Check their pricing, availability calendars, and reviews.
- Weight your comps. Not all comps are equal. A property two blocks from the water with no pool is not a strong comp for a direct waterfront listing. Prioritize the most similar ones.
- Build your baseline estimate. Average the ADR and occupancy of your best comps and use those numbers as your starting forecast inputs.
- Layer in your specific costs. Apply your actual or estimated operating expenses to convert gross income into NOI.
Here’s a quick comparison of two common Cape Coral property types to show how forecasts can differ dramatically even within the same market:
| Property type | ADR estimate | Occupancy estimate | Est. annual revenue |
|---|---|---|---|
| Waterfront pool home (4BR) | $380/night | 72% | $79,000+ |
| Inland family home (3BR) | $220/night | 65% | $42,000+ |
These figures are illustrative ranges, not guarantees — your property’s actual performance will vary based on how well you manage listings, pricing strategy, and guest experience. For more on squeezing the most out of your listing, check out maximizing Cape Coral rental profits and optimizing short-term pricing.
Pro Tip: Never rely solely on national average ADR or occupancy data when forecasting a Cape Coral property. Florida Gulf Coast markets behave differently from markets in Tennessee or Arizona. Local comps are everything. A national benchmark can mislead you into overestimating what your property will actually earn.
Building reliable forecasts: Beyond basic formulas
You’ve seen how basic forecasting works, but real-world income never matches the spreadsheet exactly. Here’s how savvy owners go deeper.
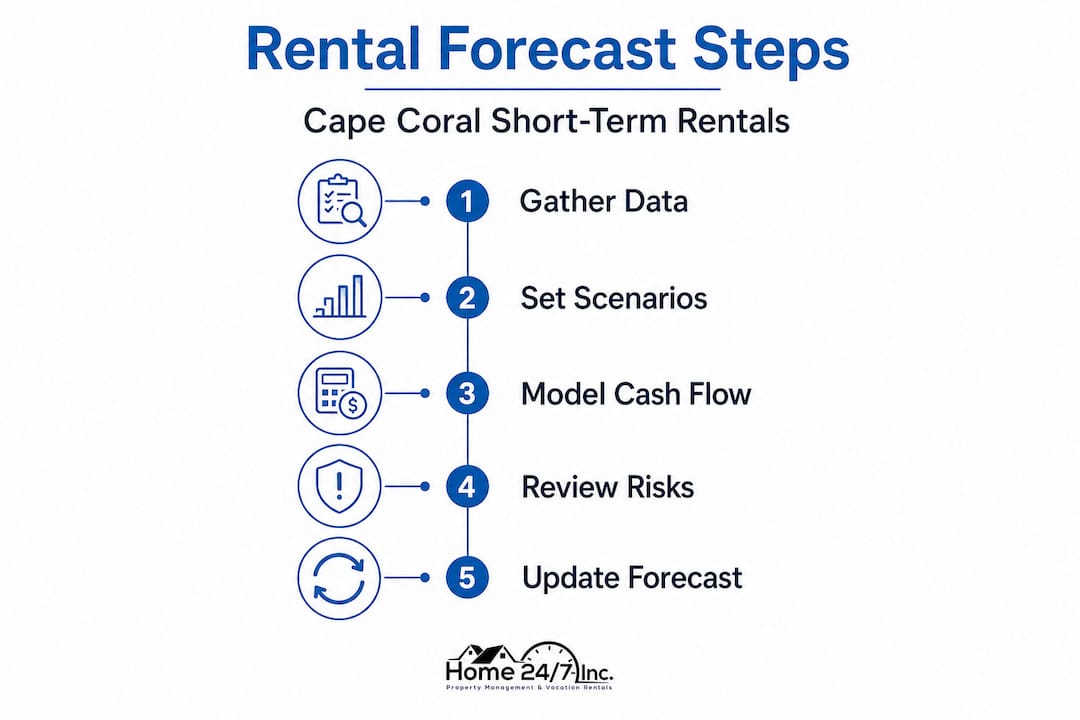
The biggest mistake investors make is treating a forecast as a single precise number rather than a range. A single estimate is called a point estimate, and while it looks tidy in a spreadsheet, it’s dangerously overconfident. Professionals run sensitivity and stress tests — modeling lower occupancy, higher costs, or longer vacancies — to understand how fragile their cash flow really is if things go sideways.
Common stress-test scenarios to model for Cape Coral:
- Low occupancy month: What if you hit only 45% occupancy in June instead of your forecasted 65%?
- Rate compression: What if competing properties drop prices and you have to match them to stay booked?
- Unexpected repairs: An AC unit fails in August — Cape Coral’s busiest, hottest month. That’s a $4,000 surprise.
- Hurricane-related vacancy: A major storm warning clears out bookings for two weeks. It happens.
- Increased management costs: Your cleaning crew raises rates, or you need a handyman on retainer.
Let’s put real numbers to this. Suppose your baseline forecast for a 3-bedroom Cape Coral rental predicts $48,000 in annual gross income at 68% occupancy. Run three scenarios:
- Best case (75% occupancy): ~$53,000 gross, roughly $35,000 NOI after expenses.
- Average case (68% occupancy): ~$48,000 gross, roughly $30,500 NOI.
- Worst case (55% occupancy): ~$39,000 gross, roughly $21,500 NOI.
That worst-case scenario might still cash flow positively — or it might not. Knowing that ahead of time lets you decide whether to buy, pass, or negotiate a lower purchase price.
It’s also worth knowing that comp-based models have real limitations. Properties with unique features — an unusual lot, an unconventional layout, or a location in a micro-neighborhood with fewer comps — produce less statistically stable projections. The fewer similar properties in your area, the wider your forecast range should be. This is why forecasts are most powerful as range-planning tools, not crystal balls.
Pro Tip: Most first-time Cape Coral investors forget to model income risk into their lender calculations. If your mortgage approval is based on 70% occupancy and you hit 55% for three months, your DSCR (debt service coverage ratio) can fall below the lender’s threshold. Always stress-test your cash flow before you close a deal, and use forecasting tools for managers to stay ahead of the curve.
For owners ready to dig further into maximizing short-term income, scenario modeling should be part of your annual review, not just a one-time exercise at acquisition.
NOI, cash flow, and using forecasts to make decisions
With a realistic, risk-aware forecast, you can make smarter decisions for your property or portfolio. Here’s how these numbers transform into action in Cape Coral’s market.
Let’s connect the dots between forecasting and actual decision-making. Net operating income (NOI) is the heartbeat of rental property valuation. As rental property analysis makes clear, property value and lender underwriting often rely on a property’s annual income after operating expenses but before financing costs. Simple metrics like gross rent multiplier (GRM) exist, but they don’t capture vacancies and operating costs the way a proper forecast does.
Here’s how to move from a forecast to action:
- Calculate your NOI. Gross income minus all operating expenses (not including mortgage payments). This is your property’s economic engine.
- Estimate cash flow. Subtract your annual mortgage payments from NOI. Positive cash flow means the property is paying you. Negative cash flow means you’re subsidizing it.
- Check your DSCR. Lenders want to see that your NOI covers your debt payments by a comfortable margin, typically 1.2x or higher. Florida DSCR loan requirements mean vacancy and income risk assumptions must be explicitly built into your forecast, even for properties that are currently fully booked.
- Compare investment options. Use NOI to benchmark competing properties. A property with a slightly lower purchase price but weaker NOI might actually be a worse deal.
- Plan capital improvements. If adding a pool bumps your ADR by $60/night and increases occupancy by 8%, you can model whether the renovation pays for itself within three years.
- Refinance strategically. When your property appreciates and NOI grows, an updated forecast can support a cash-out refinance at better terms.
“Skipping vacancy in your income forecast is like planning a road trip without accounting for gas stops. It feels optimistic until you’re stranded on I-75 in the Florida heat.”
Connecting your forecast to luxury rental income strategies is especially valuable if you own or are targeting premium Cape Coral properties, where ADR swings can have an outsized impact on annual returns.
Our take: What most Cape Coral investors miss in income forecasting
Now that you understand the technical side, here’s what our experience managing rentals in Cape Coral since 2017 has revealed — the things that standard guides almost always leave out.
The single most common mistake we see? Investors who treat their forecast as a target instead of a range. They build a spreadsheet, hit 72% occupancy in year one, and assume that number is now their baseline forever. Then a new canal-front community opens nearby with 40 shiny listings, and suddenly their bookings dip to 61%. The investors who handled it well had already modeled that scenario. The ones who hadn’t started panicking and slashing prices in a way that hurt their long-term positioning.
Local factors in Cape Coral genuinely don’t show up in national comps, and that matters more than most guides admit. A construction project on a major road near your property can dent occupancy for months. A well-publicized community event can spike demand in ways no historical data predicted. Hurricane season uncertainty can soften bookings as early as July for some guest demographics. These are Cape Coral realities, and a forecast built purely on algorithm-generated comps won’t automatically account for any of them.
Experienced owners we work with run a best-case, worst-case, and baseline scenario every single January. They revisit their forecasts mid-season when real occupancy diverges from projections. They stay nimble.
Pro Tip: Build a cash cushion equal to at least two months of operating expenses before you need it. Cape Coral’s off-season can stretch your reserves faster than you expect, especially if you get hit with an AC replacement, a roof inspection, or an unexpected gap in bookings.
Here’s the reframe we always share: forecasting is about preparation, not prediction. Nobody predicts Cape Coral’s weather perfectly, and nobody predicts the rental market perfectly either. What preparing Cape Coral rentals correctly actually means is building a financial framework that lets you survive the bad months and thrive in the good ones.
“In Cape Coral, owning your numbers means outlasting the surprises, not just maximizing the good times.”
Take forecasting further with Cape Coral property experts
As you move from learning to implementing, it’s worth considering how experts can save you time and boost returns — especially in Cape Coral’s active market.
Building a solid rental income forecast takes time, local knowledge, and a lot of spreadsheet patience. That’s exactly why many Cape Coral property owners choose to work with a management team that handles the heavy lifting for them.
At home24seven.com, we’ve been helping Cape Coral rental owners turn projections into real profit since 2017. We provide remote rental management for owners who aren’t always on the ground, backed by transparent property management practices that keep you informed every step of the way. From advanced forecasting and dynamic pricing to guest communication and maintenance coordination, our full-service Cape Coral management team takes the guesswork out of owning a short-term rental in one of Florida’s most exciting markets. Reach out and let’s talk numbers.
Frequently asked questions
How do I estimate rental income for a new property in Cape Coral?
Use local Cape Coral market data for ADR and occupancy benchmarks, then model several scenarios — best, average, and worst case — to project realistic revenue ranges after factoring in your operating expenses and potential vacancies.
What’s the difference between a rental forecast and simply using past income?
A rental forecast considers current market data, competition, and risk factors, while past income only reflects history and may miss changing trends or seasonal shifts. As rental income forecasting shows, projecting demand and pricing forward is fundamentally different from looking backward.
How can I make my Cape Coral rental forecasts more accurate?
Use multiple local comps, update your forecasts regularly throughout the year, and stress-test for worst-case scenarios like low occupancy or unexpected expenses. Keep in mind that comp-based models can be less reliable for unique properties with fewer comparable listings in the area.
Why do lenders care about vacancy and income risk?
Lenders use vacancy and income risk assumptions to judge whether your property can reliably cover loan payments even during slow periods. Florida DSCR loan guidelines require these assumptions to be explicitly built into your financial projections, not ignored.
What tools or services are best for forecasting Cape Coral rental income?
Data-driven tools are useful for benchmarking ADR and occupancy using market comps and historic listing data, while a professional local property manager can build personalized, scenario-based forecasts tailored specifically to your Cape Coral property.

