

TL;DR:
- Rental property insurance is specialized, covering structures, liability, loss of income, and tenant injuries.
- In Cape Coral, owners must address flood and hurricane risks with separate policies, as standard coverage often excludes them.
- Proactive strategies like wind mitigation and policy reviews help owners avoid costly gaps and ensure proper protection.
If you own a rental property in Cape Coral and you’re relying on a standard homeowners policy to cover it, you might be in for a very expensive surprise. This sun-drenched corner of Southwest Florida is gorgeous, no question, but it also sits squarely in hurricane country, nestled among hundreds of canals that can flood faster than you can say “where did I put that policy binder?” Understanding rental property insurance here isn’t just a nice-to-have, it’s the difference between recovering from a storm and losing everything you’ve built. This guide walks you through every layer of coverage, compliance, and Cape Coral-specific risk so you can protect your investment the right way.
Table of Contents
- What is rental property insurance and how is it different from homeowners insurance?
- Florida and Cape Coral requirements: What you must (and should) carry
- Hurricane, flood, and Cape Coral’s key perils: What your policy may miss
- Common gaps, coverage mistakes, and pro strategies
- Choosing the right policy: Florida forms, special needs, and expert insights
- The real cost of ignoring insurance gaps in Cape Coral rentals
- Ready to protect your Cape Coral rental and maximize returns?
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Rental insurance is specialized | Standard homeowners insurance does not protect rental property income, liabilities, or tenant-related risks. |
| Floods require extra coverage | Flood damage is not included in landlord policies and must be insured separately in Cape Coral. |
| Compliance is multi-layered | While Florida law does not require landlord insurance, lenders and HOAs mandate strict levels for rentals. |
| Local risks demand vigilance | Hurricane deductibles, flood exclusions, and changing market rules mean annual policy reviews are essential. |
| Pro strategies minimize gaps | Bundling, requiring tenant insurance, and choosing the right policy type elevate both protection and savings. |
What is rental property insurance and how is it different from homeowners insurance?
Let’s clear up the single biggest misconception in rental property ownership. A lot of investors assume their regular homeowners policy travels with them when they start renting out a property. It doesn’t. The moment you hand keys to a paying tenant, that standard policy often becomes voided or, at minimum, wildly inadequate.
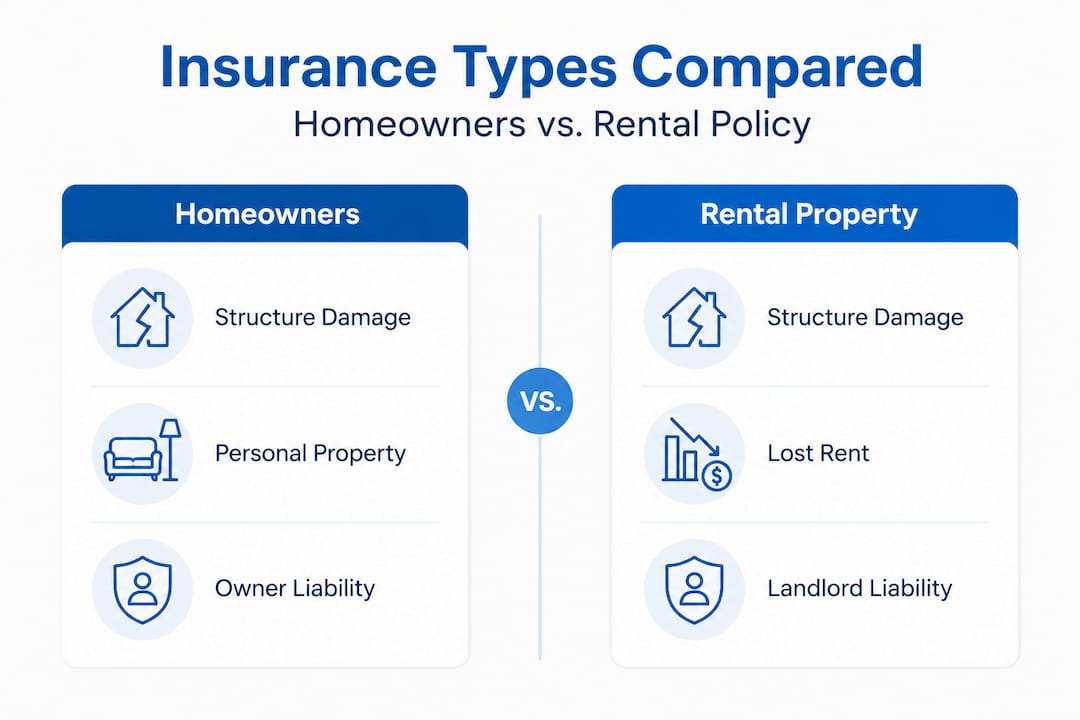
Rental property insurance (also called landlord insurance) is a specialized product built for properties that generate income. According to insurance for rental homes, core coverages include dwelling protection for structure repairs caused by fire, wind, or vandalism; liability coverage for tenant or visitor injuries including legal fees and medical costs; and loss of rental income if the property becomes uninhabitable due to a covered peril, typically covering up to 12 months of fair rental value. That last one is a gem that homeowners policies almost never include.
Here’s a quick look at how the two policy types compare:
| Feature | Homeowners insurance | Landlord (rental) insurance |
|---|---|---|
| Structure damage | Yes | Yes |
| Personal liability | Yes | Yes (higher limits) |
| Loss of rental income | No | Yes |
| Tenant injury coverage | Limited | Yes |
| Tenant belongings | Yes (yours) | No |
| Applies to rental use | Often voided | Yes |
The gap is real, and it bites hard. Imagine a tenant slips on a wet floor, breaks a wrist, and sues you. Your homeowners policy might deny the claim entirely because the home was occupied by a paying renter. Suddenly you’re paying attorney fees out of pocket. That’s not a hypothetical. It happens regularly.
For a deeper look at policy specifics, our Florida rental insurance guide covers the details in full.
“Think of landlord insurance as your homeowners policy’s more serious, business-minded sibling. Same family, totally different job.”
Florida and Cape Coral requirements: What you must (and should) carry
Once you understand the basic coverages, it’s critical to know what’s actually required, or just strongly recommended, if you rent out property in Cape Coral.
Here’s the straight truth: Florida does not legally require landlord insurance at the state level. But before you exhale with relief, pump the brakes. Mortgage lenders almost universally mandate it. HOAs and condo associations frequently require minimum liability coverage of $300,000 or more. And if you’re running a vacation rental, local Cape Coral ordinances layer on additional compliance requirements that can trip up even experienced investors.
So what should you actually carry? Here’s a practical checklist:
- Dwelling coverage at full replacement cost, not actual cash value (more on that shortly)
- Liability coverage of at least $300,000, ideally $500,000 or more
- Loss of rental income coverage to bridge revenue gaps after a disaster
- Flood insurance as a completely separate policy (standard policies never cover flood)
- Hurricane windstorm coverage confirmed in writing, not assumed
If your property is in an HOA community, read those bylaws carefully. Many Cape Coral communities explicitly require landlord policies with specific minimum thresholds, and failing to comply can expose you to fines and legal liability from the association itself.
Cape Coral’s vacation rental market also comes with its own set of rules. You’ll want to stay current with Florida vacation rental laws and the broader rental regulations for homeowners in Florida to make sure your insurance aligns with your operating license.
After Hurricane Ian in 2022, the insurance market in Southwest Florida shifted dramatically. Non-renewals spiked. Premiums jumped. Several major carriers reduced their Florida exposure entirely. This isn’t a market where you can shop once and forget about it.
Hurricane, flood, and Cape Coral’s key perils: What your policy may miss
Beyond general rules, Cape Coral’s climate and geography introduce risks that standard insurance often misses, demanding closer attention to your policy details.
Cape Coral is not your average rental market. It has over 400 miles of canals, sits close to the Gulf of Mexico, and gets visited by major storms more often than most property owners would like to admit. The standard landlord policies in Fort Myers and Cape Coral exclude flood entirely. Flood insurance must be purchased separately through the National Flood Insurance Program (NFIP) or a private carrier, and there’s a critical 30-day waiting period before a new flood policy kicks in. So you can’t buy it when a storm is already forming in the Gulf.
Flood premiums in Cape Coral typically run between $700 and $2,000 per year, sometimes higher depending on your flood zone designation. That’s a significant but non-negotiable line item if you want real protection.
Here’s how the main Cape Coral perils break down:
| Peril | Covered by standard landlord policy? | Separate coverage needed? |
|---|---|---|
| Wind damage | Yes | No |
| Hurricane wind | Yes (with deductible) | No |
| Storm surge (flooding) | No | Yes, flood policy |
| Rising water/flood | No | Yes, flood policy |
| Fire/vandalism | Yes | No |
| Sinkhole | Often excluded | Endorsement needed |
One thing that catches a lot of owners off guard: wind damage is covered, but storm surge is classified as flood. So if Ian-level winds rip off your roof, that’s a wind claim. If the water that follows those winds surges into your first floor, that’s a flood claim. Two separate policies. Two separate deductibles.
Speaking of deductibles, hurricane deductibles work differently from regular deductibles. Instead of a flat dollar amount, they’re calculated as a percentage of your home’s insured value, typically 2% to 5%. On a $500,000 property, that’s $10,000 to $25,000 out of pocket before coverage kicks in.
Pro Tip: Schedule a wind mitigation inspection. A licensed inspector documents features like reinforced roof straps, impact-resistant windows, and secondary water barriers. Presenting these findings to your insurer can cut rates by up to 40%, which is real money over time.
For a broader view of managing flood and hurricane risks in Cape Coral, we break down exactly what local investors should be tracking.
Common gaps, coverage mistakes, and pro strategies
Understanding the big risks is only half the battle. Here’s where Cape Coral landlords often get tripped up by policy fine print and practical pitfalls.
Even experienced property owners miss these common coverage gaps. According to landlord insurance resources in Florida, several edge cases consistently catch owners off guard:
- Tenant belongings are never covered. Your landlord policy protects the structure and your liability, not your tenant’s laptop or furniture. Require renters insurance in your lease agreement. It’s simple, it’s legal, and it shifts liability.
- Vacancy clauses are sneaky. Most landlord policies limit coverage if the property is empty for 30 to 60 consecutive days. During slow season or between tenants, you may unknowingly lose protection against vandalism, water damage, and more.
- Older roofs get downgraded. If your roof is aging, insurers may only pay actual cash value (ACV) rather than replacement cost value (RCV). An ACV payout on a 15-year-old roof might cover a fraction of the actual replacement cost. That gap is yours to fill.
- Pools, pets, and amenities raise your liability. A waterfront pool sounds like a great amenity, and it is until someone gets hurt. These features increase your liability exposure and may require higher coverage limits or specific endorsements.
- Short-term rentals need a different policy entirely. If you’re running a vacation rental through Airbnb or VRBO, a standard landlord policy likely won’t cover you. You need a commercial policy or an STR-specific (short-term rental) policy designed for frequent guest turnover.
On the savings side, smart strategies can reduce your premiums significantly. Florida Risk Partners recommends several approaches: bundling multiple policies for discounts, raising your deductible deliberately to lower your premium, scheduling that wind mitigation inspection (which can reduce rates by 20% to 40%), carrying an umbrella policy if you own multiple properties, and requiring tenants to carry renters insurance to shift negligence risk away from you.
Pro Tip: Make renters insurance a non-negotiable lease term. If a tenant’s dog bites a visitor, their renters policy responds first. That’s one less headache landing on your doorstep.
If you’re getting started with hosting, our guide on preparing for short-term rentals in Cape Coral covers the full setup process.
Choosing the right policy: Florida forms, special needs, and expert insights
With gaps identified, it’s time to understand which policy forms, endorsements, and upgrades best suit your unique rental and risk profile in Cape Coral.
Florida landlord policies come in three main forms. Think of them as bronze, silver, and gold.
- DP-1 (Basic form): Covers only named perils like fire and lightning. Very limited. Pays actual cash value. Not recommended for most Cape Coral rentals.
- DP-2 (Broad form): Adds more named perils including windstorm and falling objects. Better, but still limited in scope.
- DP-3 (Special form): The gold standard. Covers all perils except those explicitly excluded. Pays replacement cost on the dwelling. This is the recommended choice for broad dwelling protection, especially in a high-risk area like Cape Coral.
One often-overlooked coverage is ordinance and law protection. If your property is damaged and needs to be rebuilt, local building codes may require upgrades like new electrical panels, hurricane straps, or impact windows that weren’t in the original construction. Without ordinance/law coverage, you pay for those code-required upgrades out of pocket. In an older Cape Coral home, that bill can be substantial.
Roof age is another big issue in Florida’s current market. Many insurers are non-renewing policies on homes with roofs over 15 years old. If your rental has an aging roof, you may suddenly find yourself scrambling for coverage, often at much higher rates through surplus lines carriers. Getting ahead of this with a roof inspection or replacement before renewal can make a significant difference.
“The right policy isn’t just about today’s premium. It’s about what actually pays out after the storm is gone and the damage is real.”
Smart annual habits also matter. Review your coverage every year, especially after each storm season. Property values shift. Rental rates change. Your insured value should reflect what it would actually cost to rebuild, not what you paid for the property years ago.
The real cost of ignoring insurance gaps in Cape Coral rentals
Here’s our honest take after years of working with Cape Coral rental owners: most insurance mistakes don’t look like mistakes until it’s far too late.
The “checkbox” approach to insurance, where you buy the cheapest policy that technically satisfies your lender and call it done, works fine right until it doesn’t. And in Cape Coral, “doesn’t” tends to arrive with 150-mile-per-hour winds and ten feet of storm surge.
Florida landlord premiums already run 15% to 25% higher than standard homeowners policies. Add flood coverage, and you’re looking at an additional $700 to $2,000 annually. Post-Ian, non-renewals became common across Southwest Florida as carriers pulled back from the market. That’s the reality of owning rentals here, and pretending it isn’t expensive won’t protect your balance sheet.
What we’ve seen work consistently is a proactive, customized strategy. Owners who invest in wind mitigation inspections, maintain updated roofs, carry adequate liability limits, and work with insurance agents who specialize in Florida investment properties consistently come out ahead after a loss. They recover faster. They avoid coverage disputes. And they often pay less in premiums over time despite carrying more coverage.
The most overlooked piece? Working with a property management partner who actually understands the local insurance landscape. Knowing when your vacancy clause kicks in, which endorsements your vacation rental needs, and how to document your property for faster claims isn’t expertise most investors build on their own. It’s expertise you borrow from people who live and breathe this market every day.
Ready to protect your Cape Coral rental and maximize returns?
If all of this feels like a lot to track on top of managing guests, maintenance calls, and seasonal pricing, you’re not wrong. Insurance compliance is genuinely complex in Cape Coral, and it’s one of the areas where a small oversight can cost you tens of thousands of dollars.
That’s exactly why we do what we do at Home 24/7. Our property management for Cape Coral rentals includes helping owners navigate the compliance requirements that go hand in hand with running a successful, protected rental. From confirming your policy aligns with local regulations to keeping vacancy windows in check so your coverage never lapses, we’ve got your back. Take a look at our complete insurance guide for even more detail, or reach out directly for a consultation tailored to your specific Cape Coral property.
Frequently asked questions
Does landlord insurance cover hurricane or flood damage in Cape Coral?
Standard landlord policies cover wind but exclude flood entirely. Flood insurance must be purchased separately through NFIP or a private carrier, with a 30-day waiting period before it takes effect.
Can I require my tenants to get renters insurance?
Yes, landlords in Florida can and should require tenants to carry renters insurance as a lease condition. This protects tenant belongings and shifts liability for tenant-caused damage away from your landlord policy.
What is a hurricane deductible for landlord insurance?
A hurricane deductible is typically 2% to 5% of your property’s insured value, meaning on a $400,000 home, you pay $8,000 to $20,000 before coverage starts for wind damage.
What happens if my rental is vacant for longer than allowed in the policy?
If your property sits empty beyond the policy’s vacancy limit of 30 to 60 days, your insurer may reduce or deny claims for vandalism, water damage, or other perils during that period.
Are older Cape Coral homes harder to insure for rentals?
Absolutely. Homes with roofs older than 15 years face a higher risk of non-renewal in Florida’s current market, and those that do get renewed may only receive actual cash value payouts rather than full replacement cost.

