

TL;DR:
- Standard Florida homeowners policies often do not cover short-term rental damages or liability.
- Florida’s weather and legal environment necessitate specialized vacation rental insurance with additional coverage.
- Many owners face costly coverage gaps, especially with flood, windstorm, and liability requirements.
You bought a gorgeous Cape Coral canal home, listed it on Airbnb, and thought your regular homeowners policy had you covered. Surprise! Most standard Florida homeowners policies treat short-term rentals like an uninvited guest. They simply refuse to pay. 78% of vacation hosts have coverage gaps, with denied claims hitting as high as $15,000. That’s a lot of sunscreen money going down the drain. In this guide, we’ll walk you through what vacation rental insurance actually covers, what Florida law and lenders expect from you, and how to protect your property without losing sleep or your profit margin.
Table of Contents
- Understanding vacation rental insurance for Florida properties
- Florida-specific insurance requirements and risks
- Common coverage gaps and claims surprises
- Expert strategies to save on vacation rental insurance
- Why most Florida owners underestimate vacation rental risk
- Explore smarter property protection options
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Homeowners policies exclude rentals | Most standard policies do not protect Florida vacation rental properties against guest-related losses. |
| Florida has unique insurance needs | Separate windstorm deductibles and flood coverage are required for proper protection in Florida. |
| Gaps leave owners exposed | 78% of Florida hosts have insufficient coverage, risking denied claims or out-of-pocket losses. |
| Platform guarantees are limited | Airbnb or Vrbo offer only partial liability coverage, with many exclusions and short claim windows. |
| Expert help lowers insurance costs | Professional management and risk-reducing strategies can keep your premiums affordable without sacrificing coverage. |
Understanding vacation rental insurance for Florida properties
Now that you know the risks of coverage gaps, let’s define exactly what vacation rental insurance does and does not cover.
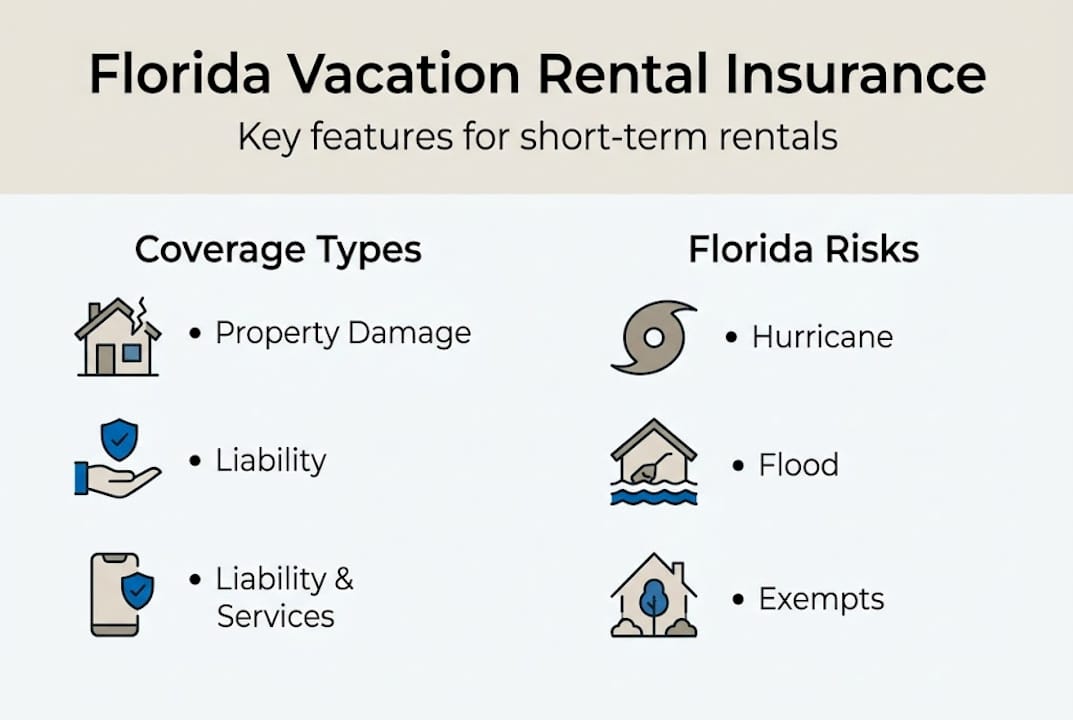
Vacation rental insurance is a specialized policy designed for properties rented out on a short-term basis, typically fewer than 30 days at a time. Think of it as a hybrid between a commercial landlord policy and a homeowners policy, built specifically for the quirks of hosting strangers in your home. It covers property damage, liability for guest injuries, and in many cases, lost rental income when something goes wrong.
Your standard HO-3 homeowners policy is built for owner-occupied homes. The moment paying guests walk through the door, most of those protections evaporate. HO-3 policies often deny rental-related claims outright, treating the rental activity as an undisclosed commercial operation. That’s not a loophole. That’s intentional policy language.
So what about Airbnb’s AirCover or Vrbo’s liability guarantee? They sound great in the marketing materials, but they come with major limitations. Neither platform program covers lost rental income. Intentional damage by guests is often excluded. Time windows to file claims are short and strict. Liability limits are capped in ways that may not satisfy your mortgage lender or HOA. Think of platform guarantees like a travel umbrella: fine for a light drizzle, not so great for a Category 4 hurricane.
Here’s a quick comparison to clarify how these options stack up:
| Coverage type | Property damage | Liability | Lost income | Guest injuries |
|---|---|---|---|---|
| HO-3 homeowners policy | Rarely | Rarely | No | No |
| Airbnb AirCover | Limited | Limited | No | No |
| Vacation rental insurance | Yes | Yes | Often yes | Yes |
Vacation rental insurance fills those gaps. Core features typically include:
- Property damage coverage for guest-caused damage beyond normal wear
- Liability protection for guest injuries on the premises
- Loss of rental income when repairs make the property unrentable
- Theft coverage for personal belongings and furnishings
- Vandalism protection even when intentional
If you’re also navigating Florida vacation rental licensing, having the right insurance in place is often part of meeting compliance requirements. And staying on top of rental law requirements will help you understand what coverage thresholds regulators and lenders actually expect.
Florida-specific insurance requirements and risks
Understanding the coverage basics, let’s focus on what makes Florida unique, including the weather and legal requirements that impact your policy choices.
Florida is not your average rental market. You’ve got sunshine, beaches, tourists in flip-flops, and also, one of the most demanding insurance environments in the country. Being a vacation rental owner here means understanding rules that simply don’t exist in most other states.
First up: windstorm and hurricane deductibles. Unlike a standard flat-dollar deductible, Florida’s windstorm deductibles are percentage-based and calculated against your home’s insured value. So on a $500,000 Cape Coral property with a 2% hurricane deductible, you’d be on the hook for $10,000 before your insurer pays a single cent. That number grows with your property value.
Flood insurance is a whole other story. Standard vacation rental policies do not include flood coverage. You need a separate policy, either through the National Flood Insurance Program (NFIP) or a private insurer. Given that Cape Coral sits in a flood-prone region with an impressive 400+ miles of canals, skipping flood insurance is the kind of gamble that doesn’t end with a funny story.
“Flood insurance is not included in standard vacation rental policies. Owners in flood-prone areas like Cape Coral must purchase separate coverage, often through NFIP or private carriers.”
Mortgage lenders and HOAs also have a say in your coverage. Most require proof of at least $1 million in liability protection before they’ll sign off on a short-term rental operation. Florida doesn’t have one statewide mandate for vacation rental insurance, but local regulations and market pressures create strong expectations regardless.
Here’s a snapshot of Florida-specific considerations:
| Risk factor | What it means for you |
|---|---|
| Hurricane deductible | Percentage of insured value, not a flat dollar amount |
| Flood risk | Separate policy required, often NFIP |
| Liability minimum | $1M commonly required by lenders and HOAs |
| Storm season | June through November, premium spikes possible |
Pro Tip: Review your flood zone designation on FEMA’s maps before purchasing a policy. Cape Coral properties in Zone AE carry the highest flood risk, and NFIP rates vary significantly based on your elevation certificate.
Common coverage gaps and claims surprises
Knowing Florida’s unique needs, it’s crucial to identify where most owners overlook real risks, often with painful financial results.
Let’s paint a picture. A guest throws a pool party. Things get rowdy. Someone breaks the outdoor furniture, the sliding glass door, and their ankle on the way out. Under your HO-3, none of that is covered because the property was being rented. Under Airbnb’s AirCover, the damage claim might be accepted but only if you report it within 14 days and have photo documentation. The medical liability for the ankle? That’s likely on you.
This kind of scenario plays out more than you’d think. In fact, 78% of Florida vacation hosts have coverage gaps, and real denied claims reaching $15,000 have been documented under HO-3 policies. That’s not a hypothetical. That’s someone’s actual loss.
Here are the most common coverage gaps that catch Florida rental owners off guard:
- Lost rental income: If a storm or damage makes your property unrentable for three weeks during peak season, platform programs won’t replace that income.
- Intentional guest damage: Many policies and platform programs exclude deliberate destruction, which is more common than you’d hope.
- Liability for off-property incidents: If a guest gets hurt launching a kayak from your dock, your liability exposure might extend beyond your property line.
- Theft by guests: Some standard policies won’t cover theft when you’ve voluntarily let someone into your home.
- Pet damage: You said no pets. The dog says otherwise. Most policies exclude pet-related damage unless specifically added.
Platform guarantees also have tight filing windows, often as short as 14 days, and require extensive documentation most hosts aren’t prepared to provide on short notice.
Pro Tip: Keep a timestamped photo log of your property before and after every guest stay. It’s your best defense if a damage claim gets disputed, and it dramatically speeds up the claims process.
Working with a professional management team can reduce these risks significantly. Routine property inspections, guest vetting, and documented condition reports create a paper trail that makes claims smoother and less stressful. Properties that maximize rental income through professional management also tend to attract more responsible guests in the first place.
Expert strategies to save on vacation rental insurance
After seeing the risks, here are proven strategies Florida owners use to get the right protection and save on premiums.
Vacation rental insurance in Florida doesn’t have to wreck your budget. With the right approach, you can get solid coverage and keep more money in your pocket. Here’s how savvy owners do it:
-
Choose admitted carriers over surplus lines when possible. Admitted insurers are approved and regulated by Florida’s state insurance department, which means they offer more stable claims processes and coverage guarantees. Surplus lines carriers operate outside that oversight and can be less predictable. Admitted insurers provide more stable claims experiences for short-term rental owners.
-
Bundle your policies. If you own multiple properties, or even just want to combine your vacation rental, auto, and umbrella policies under one insurer, bundling typically earns you a meaningful discount. Some Florida insurers offer up to 15% off for bundled packages.
-
Hire professional property managers. This one might surprise you. Insurers love professional management because it means regular inspections, maintained properties, and lower claims frequency. Working with local property managers in Cape Coral can actually lower your premiums by reducing perceived risk. Understanding management fees upfront helps you see the full financial picture.
-
Install safety features. Smoke detectors, carbon monoxide alarms, smart locks, and security cameras signal to insurers that you take risk seriously. Many carriers offer discounts for documented safety upgrades.
-
Opt for higher deductibles. Raising your deductible from $1,000 to $2,500 can meaningfully reduce your annual premium. Just make sure you have the liquidity to cover that deductible if a claim hits.
Pro Tip: Ask your insurer directly what risk-reduction measures earn discounts on your specific policy. Not all carriers publish these criteria, but many will tell you if you ask.
Shopping around annually is also smart. Florida’s insurance market shifts constantly, and the best rate from two years ago might not be competitive today.
Why most Florida owners underestimate vacation rental risk
Let’s step back and examine why these gaps persist and what most articles leave out.
Here’s the uncomfortable truth: most vacation rental owners don’t discover their coverage gaps until they file a claim and get denied. It’s human nature to assume the policies we pay for actually cover the things we’re worried about. But in Florida’s short-term rental world, that assumption is expensive.
The bigger issue is that platform guarantees are marketed so confidently that many hosts genuinely believe they’re covered. They’re not. As we’ve noted, HO-3 policies frequently deny rental claims, and most short-term rental hosts, a full 78%, are carrying real exposure without knowing it.
Florida layers on extra complexity with its storm season, flood zones, and a legal environment that moves fast. A policy adequate in 2024 might not keep pace with what lenders or HOAs require in 2026. The property management strategies that protect your bottom line aren’t just about bookings. They’re about making sure the money you earn doesn’t vanish in a single denied claim. Treating your rental like a real business, with the right specialized insurance to match, is what separates savvy investors from stressed-out ones.
Explore smarter property protection options
If you’re ready to take the next step in protecting your property and income, we’re here to help.
At Home24Seven, we’ve been helping Cape Coral owners navigate the full complexity of vacation rental ownership since 2017. That includes making sure your property is set up in ways that actually protect your investment, from guest vetting and routine inspections to compliance support that keeps your coverage valid.
Our remote rental management solutions are built for owners who want peace of mind without the headaches. We offer transparent management solutions with no hidden surprises, and our full-service management packages are designed to reduce your risk exposure while maximizing your rental income. Reach out and let’s talk about what that looks like for your property.
Frequently asked questions
Does homeowners insurance cover my Florida vacation rental?
Most standard homeowners (HO-3) policies in Florida deny claims for rental-related damage or liability, so specialized vacation rental insurance is needed to protect your property and income.
Does Airbnb or Vrbo provide enough insurance protection for Florida hosts?
No. Platform guarantees exclude lost rental income and intentional damage, carry strict filing windows, and have liability caps that often don’t meet lender or HOA requirements.
What liability coverage do Florida lenders and HOAs typically require for vacation rentals?
Most mortgage lenders and HOAs require proof of at least $1 million in liability coverage from a specialized short-term rental insurer before approving rental activity.
Are windstorm and flooding covered on a standard Florida vacation rental policy?
Hurricane and windstorm deductibles are percentage-based on your home’s insured value, and flood coverage requires a completely separate policy through NFIP or a private carrier.
How can I save money on vacation rental insurance in Florida?
Bundling policies, professional management, and opting for higher deductibles are the three most effective ways to reduce your annual vacation rental insurance premium in Florida.

