

TL;DR:
- Homeowner support includes federally and state-funded programs helping homeowners avoid foreclosure and cover housing-related costs during financial hardship. These programs assist with mortgage arrears, property taxes, insurance, utilities, internet, and repairs, often with additional legal and counseling services to improve long-term housing stability. Acting early and gathering proper documentation significantly increases the chances of successfully obtaining aid before funds run out or foreclosure progresses.
Homeowner support is defined as a collection of federally and state-funded programs designed to help homeowners avoid foreclosure and manage housing costs after experiencing financial hardship. The primary federal example is the Homeowner Assistance Fund (HAF), established by the American Rescue Plan Act in 2021 to prevent mortgage delinquencies, loss of utilities, and displacement for homeowners facing COVID-19-related hardships. Beyond direct cash assistance, homeowner support also includes free housing counseling, legal representation, and loss mitigation services. If you own property and hit a financial wall, understanding what is homeowner support could be the difference between keeping your home and losing it.
What does homeowner support actually cover?
Homeowner support covers far more than just your monthly mortgage payment. The HAF program guidelines spell out a broad list of eligible expenses, and knowing exactly what qualifies can save you from scrambling to cover costs you assumed were your problem alone.
Here is what homeowner assistance programs typically help with:
- Mortgage payments, including past-due amounts and arrears
- Property taxes, both current and delinquent
- Homeowners insurance premiums to keep your coverage active
- HOA fees that, if unpaid, can trigger their own foreclosure process
- Utilities including electricity, gas, and water
- Internet service, which qualifies under federal HAF rules
- Certain home repairs necessary to maintain habitability
The fact that internet and utilities are on this list surprises most homeowners. It reflects a broader definition of housing stability: if your power gets cut off, your home is no longer truly livable, even if you technically still own it.
| Cost Category | Typical Support Available |
|---|---|
| Mortgage arrears | Past-due payments plus ongoing monthly assistance |
| Property taxes | Delinquent and current tax balances |
| Homeowners insurance | Premium payments to prevent policy lapse |
| HOA fees | Overdue fees that could trigger lien or foreclosure |
| Utilities and internet | Electricity, gas, water, and broadband service |
| Home repairs | Repairs required for safe, habitable living conditions |
State programs follow the federal HAF framework but add their own rules on maximum amounts and documentation. Some states cap total assistance at $25,000, while others go higher. Oregon, for example, offered up to $50,000 for past-due mortgages plus additional monthly support. That kind of range means you cannot assume your state matches what you read about another state’s program.
Pro Tip: Map your specific hardship to the expense categories allowed under your state’s program before you apply. Practitioners find that matching hardship to categories significantly improves application success and speeds up the process.
How do homeowner support programs vary by state?
Think of state-administered homeowner support programs less like a single national product and more like 50 different products that share a brand name. The federal government funds HAF, but each state, territory, and tribal government runs its own version with its own rules. The Consumer Financial Protection Bureau (CFPB) explicitly advises homeowners to verify their specific state or tribe’s requirements before applying, because the differences are significant enough to affect eligibility entirely.
What varies from state to state includes:
- Income limits, which determine whether you qualify at all
- Maximum assistance amounts, ranging from tens of thousands of dollars to more modest caps
- Documentation requirements, such as proof of hardship, income verification, and mortgage statements
- Application portals and timelines, since some states have closed their programs while others still accept applications
- Priority populations, with some states fast-tracking assistance for veterans, seniors, or rural homeowners
Oregon’s HAF program is a strong case study. It helped 2,619 households stay in their homes by pairing financial assistance with counseling services. That combination proved more effective than money alone, because homeowners who understood their options made better decisions about loan modifications and repayment plans.
Timing matters just as much as eligibility. The HAF program is scheduled to end by September 2026 or when funds run out, whichever comes first. Several states have already exhausted their allocations. If you are considering applying, waiting is genuinely risky.
Pro Tip: Search your state housing agency’s website directly rather than relying on third-party summaries. Program rules change quickly, and outdated information could lead you to apply for assistance that no longer exists in your state.
What counseling and legal services come with homeowner support?
Money alone does not always save a home. This is the part of homeowner support that most people overlook, and it is often the piece that makes the biggest difference. Housing counseling and legal representation give homeowners the tools to negotiate with mortgage servicers, understand modification options, and defend against foreclosure in court.
New York State funds nearly 90 organizations providing free qualified mortgage-assistance services through its Homeowner Protection Program (HOPP). Critically, HOPP does not pay your mortgage directly. It provides the legal and counseling muscle to help you fight for better terms, defer payments, or avoid foreclosure through negotiation. That distinction matters because many homeowners assume they need cash assistance when what they actually need is someone who knows how to talk to a servicer.
Common types of counseling and legal help available through homeowner support services include:
- HUD-approved housing counseling for budgeting, loan modification guidance, and foreclosure prevention planning
- Loss mitigation assistance to negotiate repayment plans or forbearance agreements with your lender
- Legal representation in foreclosure proceedings, particularly in judicial foreclosure states
- Mediation services that bring homeowners and servicers to the table before court action begins
- Financial coaching to address the underlying hardship and prevent future delinquency
Oregon Housing and Community Services noted that their integrated approach of pairing payment assistance with counseling improved long-term housing stability. Homeowners who received both types of support were better positioned to stay current on payments after the assistance period ended. That is the real goal: not just surviving the crisis, but coming out the other side on solid footing.
Pro Tip: Even if you do not qualify for direct financial assistance, you may still qualify for free counseling or legal services. Search the HUD website for approved housing counselors in your area before assuming you have no options.
What should you do to access support and avoid foreclosure?
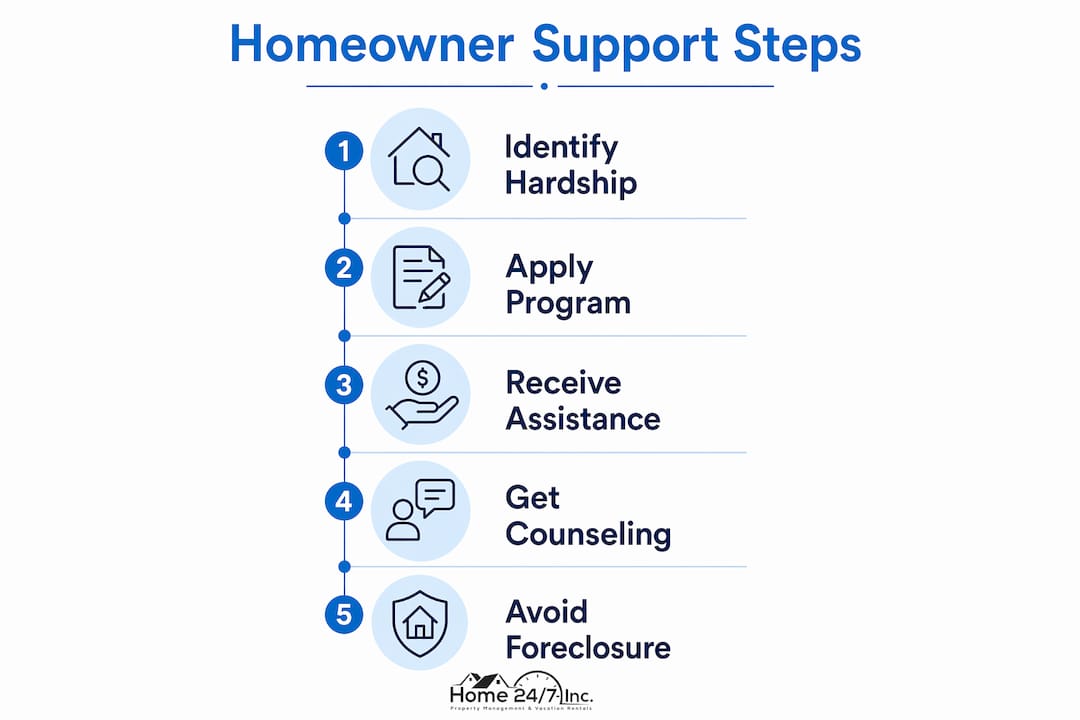
Acting early is the single most important thing you can do. Homeowner assistance programs have limited funds, and the homeowners who apply first tend to have the best outcomes. Here is a practical sequence to follow:
- Identify your specific hardship. Was it job loss, medical expenses, a death in the family? Knowing the trigger helps you match your situation to the right program category.
- List every housing cost you are struggling with. Mortgage, taxes, insurance, utilities, and HOA fees all count. Do not assume only your mortgage qualifies.
- Check your state’s HAF program status. Visit your state housing agency’s website to confirm whether the program is still accepting applications and what the income limits are.
- Gather your documentation. Most programs require proof of hardship, recent income statements, mortgage account information, and proof of homeownership.
- Apply through the official state or tribal portal. Avoid third-party services that charge fees to help you apply. The programs are free, and paid intermediaries add no value.
- Contact a HUD-approved housing counselor. Even while your application is pending, a counselor can help you negotiate with your servicer and explore modification options.
- Follow up consistently. Program administrators handle high volumes. Staying in contact and responding quickly to requests for additional documents keeps your application moving.
The CFPB’s guidance reinforces that understanding allowable expense categories before applying is one of the most practical things you can do to improve your chances. Homeowners who walk in knowing exactly what they need and why it qualifies spend less time in the application process and face fewer rejections.
Key takeaways
Homeowner support works best when financial assistance, housing counseling, and legal services are combined and pursued early before funds run out or foreclosure proceedings begin.
| Point | Details |
|---|---|
| Core definition | Homeowner support covers mortgage payments, taxes, insurance, utilities, and repairs during financial hardship. |
| Federal program | The HAF, funded by the American Rescue Plan Act, is the primary federal homeowner assistance program, ending by September 2026. |
| State variation | Each state runs its own version of HAF with different income limits, caps, and documentation rules. |
| Counseling matters | Free legal and counseling services, like New York’s HOPP program, are equally important as direct financial aid. |
| Act fast | HAF funds are limited and several states have already closed their programs, so early action is critical. |
What I have learned from watching homeowners navigate this process
Working in property ownership and management since 2017, I have seen a pattern repeat itself more times than I can count. A homeowner hits a rough patch, assumes they do not qualify for any help, and waits too long to ask. By the time they reach out, either the program has closed or the foreclosure process is already in motion. The assistance was there. The timing was not.
The other mistake I see constantly is treating financial aid and counseling as separate choices. They are not. Oregon’s data shows that homeowners who combined both had better long-term outcomes. A check that covers three months of arrears does not fix the conversation you still need to have with your servicer about what happens in month four.
Documentation is where applications die. Missing a single income statement or failing to document the hardship trigger clearly can delay or kill an application. My honest advice: treat your homeowner support application like a job application. Prepare everything before you submit, double-check every requirement, and follow up like your home depends on it. Because it does.
The programs exist. The money is real. But they reward the homeowners who show up prepared and act before the deadline, not after.
— Philipp
How Home24seven can support your property goals
Homeowner support programs help you hold onto your property during tough times. But once you are stable, the next question is how to make that property work harder for you. At Home24seven, we have been helping property owners in Cape Coral, Florida turn their homes into income-generating assets since 2017. Our remote rental management service handles everything from guest communication and booking to maintenance and revenue optimization, so you can focus on what matters without the daily headaches. If you want to understand how transparent property management fits into your long-term property strategy, we are here to walk you through it. Think of us as the property partner who actually picks up the phone.
FAQ
What is homeowner support in simple terms?
Homeowner support refers to programs that help homeowners avoid foreclosure and manage housing costs during financial hardship. The primary federal example is the Homeowner Assistance Fund (HAF), which covers mortgage payments, property taxes, utilities, and more.
Who qualifies for homeowner assistance programs?
Eligibility varies by state, but most HAF programs require proof of financial hardship related to COVID-19 after January 21, 2020, along with income limits and documentation of housing costs affected. Check your state housing agency’s website for specific requirements.
Does homeowner support only cover mortgage payments?
No. HAF funds can cover mortgage arrears, property taxes, homeowners insurance, HOA fees, utilities, internet, and certain home repairs, making it broader than most homeowners realize.
How long will homeowner assistance programs be available?
The HAF program is scheduled to end by September 2026 or when allocated funds run out, whichever comes first. Several states have already closed their programs, so applying sooner rather than later is strongly advisable.
Is free legal help available for homeowners facing foreclosure?
Yes. New York’s HOPP program funds nearly 90 organizations providing free legal and counseling services to homeowners. Similar programs exist in other states through HUD-approved housing counselors.

