

TL;DR:
- Proper property revenue tracking involves recording all income streams, such as rent, fees, and reimbursements, by property and income type. It is essential for accurate reporting, tax compliance, and making informed investment decisions, especially when using a tailored chart of accounts and appropriate accounting methods. Utilizing dedicated software and maintaining organized records helps ensure audit readiness and simplifies financial management for landlords and investors.
If you think property revenue tracking means logging your monthly rent deposit and calling it a day, you are leaving money on the table and possibly giving your accountant a headache. The industry term for this practice is rental income accounting, and it covers far more ground than most owners realize. From pet fees and parking income to utility reimbursements and forfeited deposits, every dollar your property generates needs a home in your records. Get this right, and you unlock cleaner tax filings, smarter investment decisions, and a real picture of how profitable your portfolio actually is.
Key Takeaways
| Point | Details |
|---|---|
| Beyond rent collection | Property revenue tracking covers all income streams, not just base rent payments. |
| Accounting method matters | Choosing cash vs. accrual basis affects when income is recorded and how taxes are reported. |
| Chart of accounts is foundational | Organizing income into detailed sub-accounts by property prevents costly misclassification errors. |
| Software saves real time | Dedicated platforms automate categorization and reporting, reducing manual errors across your portfolio. |
| IRS compliance depends on records | Detailed, organized income records protect you during audits and simplify Schedule E reporting. |
What property revenue tracking actually involves
So what is property revenue tracking, exactly? Think of it as the systematic process of recording, categorizing, and allocating every dollar of income your rental property generates, down to the specific property, unit, and owner it belongs to. The industry calls this rental income accounting, and the scope of it surprises most first-time landlords.
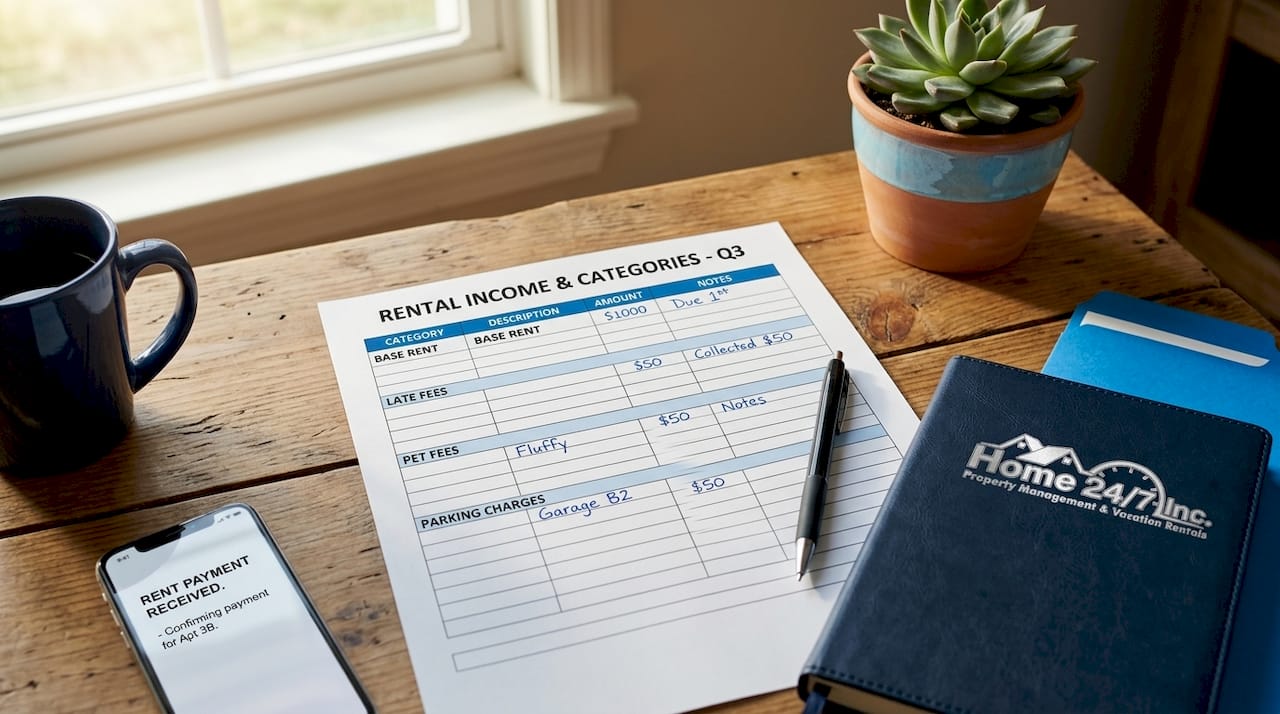
All income streams in a well-run property accounting setup include base rent, late fees, pet fees, parking charges, utility reimbursements, and forfeited security deposits. Each of these is a distinct revenue category, not just a variation of “rent.” And that distinction matters more than you might expect. A rental income statement that lumps all of these together tells you almost nothing about what is actually driving your cash flow.
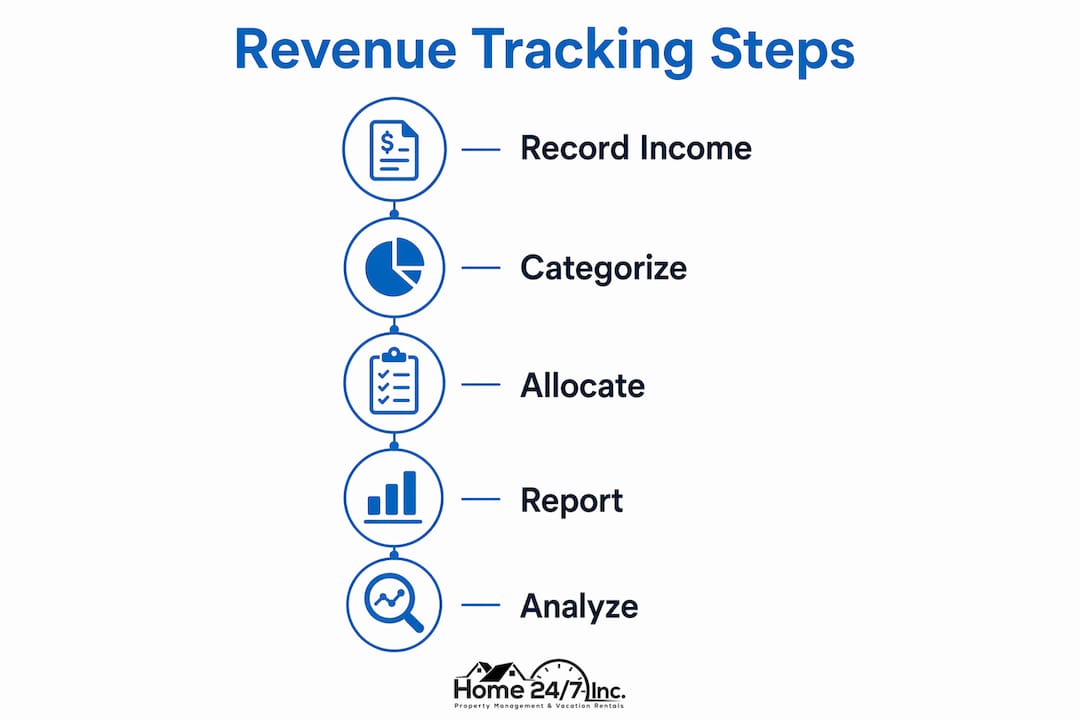
Here is where many owners go wrong: they drop everything into one “rental income” bucket and wonder why their reports feel fuzzy. When you mix base rent with a one-time pet deposit and a parking fee, you cannot tell whether a dip in revenue came from a vacancy, a pricing problem, or guests simply not opting into paid parking.
Proper property financial tracking requires allocating income by:
- Property address so you can compare performance across your portfolio
- Unit number on multi-unit properties to spot individual underperformers
- Income type (rent, fees, reimbursements) for clear profitability analysis
- Owner when managing properties on behalf of multiple investors or holding entities
Pro Tip: If you self-manage even two or three properties, set up separate income categories from day one. Retrofitting a messy chart of accounts a year later is twice the work and triple the frustration.
Cash vs. accrual: when revenue gets recorded
The accounting method you choose determines not just how your books look, but when income shows up on them. This is one of the most overlooked decisions in property revenue management.
| Method | When income is recorded | Best for | Tax implication |
|---|---|---|---|
| Cash basis | When payment is received | Small landlords, simple portfolios | Income reported in year received |
| Accrual basis | When income is earned | Larger portfolios, institutional investors | Income reported when due, not paid |
Revenue recognition timing directly affects your monthly profitability figures and how you report income at tax time. If a tenant pays January’s rent on December 30th, a cash-basis landlord records it in December. An accrual-basis landlord records it in January, when it was earned. Same money, different tax year.
For most individual property owners, cash basis is simpler and is the more common choice. Larger investors with complex portfolios often shift to accrual accounting because it provides a more accurate picture of financial performance over time. Consistency in method selection is critical. Switching between methods mid-year is an accounting nightmare and can trigger IRS scrutiny.
Pro Tip: Whatever method you pick, apply it uniformly across all your properties and document your choice. Your CPA will thank you, and so will your future self at tax time.
Why your chart of accounts changes everything
If property revenue tracking is the engine, the chart of accounts is the transmission. It determines how granularly you can see your financial performance and how much work your reports actually do for you.
A chart of accounts is simply an organized list of all the financial categories your business uses to record transactions. For rental properties, that means breaking income down into sub-accounts like this:
| Account | Sub-account examples |
|---|---|
| Rental income | Base rent, short-term rental income |
| Fee income | Late fees, pet fees, move-in fees |
| Reimbursements | Utility reimbursements, HOA pass-throughs |
| Other income | Parking fees, storage fees, forfeited deposits |
A well-designed chart of accounts lets you attach income entries to specific properties and units using tags or classes. This is how you answer questions like, “Which of my three Cape Coral properties is generating the most fee income?” or “Did my pet policy change impact revenue this quarter?”
The risks of skipping this structure are real. Overly broad income categories create rework, obscure performance trends, and can lead to misclassification on your tax return. The benefits of going granular include:
- Faster, cleaner year-end tax preparation
- Clear property-level profitability reports
- Easier identification of underperforming revenue streams
- Better data for refinancing applications or investor reporting
How to track property income effectively starts here. Without a solid chart of accounts, every other tracking tool you use is working at a disadvantage.
Tools that make revenue tracking less of a chore
Let’s be honest. Tracking rental income manually in a spreadsheet works fine when you have one property and a lot of patience. Once you hit two or three properties, things get messy fast, like trying to run a restaurant on sticky notes.
Here is a practical breakdown of your options:
- Spreadsheets are free and flexible but require you to build and maintain all your formulas, categories, and reports yourself. One formula error can cascade across months of data. Fine for getting started, not for scaling.
- General accounting software like QuickBooks can handle rental property tracking if you customize the chart of accounts correctly. The setup requires some effort upfront, but the reporting capabilities are solid.
- Dedicated rental platforms are purpose-built for property income analysis. Platforms that integrate banking with bookkeeping can automatically classify transactions into 120+ Schedule E categories, turning hours of manual entry into a few clicks.
- Full-service property management platforms handle rent collection, owner disbursements, and financial reporting all in one place. For vacation and short-term rental owners especially, this level of integration pays for itself.
When choosing a tool, match it to your portfolio size and complexity. A single long-term rental probably does not need the same platform as a portfolio of six vacation rentals generating nightly bookings, cleaning fees, and owner statements. You can also explore property management automation approaches to understand how technology is reshaping income tracking across the industry.
Pro Tip: Whatever platform you use, make sure it can generate a property-level income report with a single click. If pulling a report requires more than five minutes of work, you will stop doing it regularly, and that defeats the whole purpose.
Tax reporting and staying audit-ready
Here is where property financial tracking stops being an organizational preference and becomes a legal requirement. The IRS is clear: all rental income must be reported, and “rental income” means any payment for the use or occupation of your property. That includes pet fees, late fees, and yes, even that storage unit you are renting to your tenant for $50 a month.
Rental income is reported on Form 1040 Schedule E, broken down by property. This is exactly why property-level tracking matters so much. If your records are a jumbled mess, reconstructing them for Schedule E at tax time is painful. If they are organized with clean sub-accounts by property, the numbers practically fill themselves in.
Here is how to stay audit-ready all year long:
- Categorize income as you receive it. Do not let transactions pile up in an uncategorized account. A weekly 10-minute review beats a quarterly six-hour catch-up every time.
- Keep backup documentation. Lease agreements, fee schedules, and payment receipts are your proof. Good records protect you if the IRS asks questions, and they will ask if your numbers look inconsistent.
- Reconcile monthly. Match your bank deposits to your income records every month. Discrepancies are far easier to resolve when they are 30 days old versus 11 months old.
- Separate accounts by property. Using one bank account for multiple properties is a recipe for confusion. Dedicated accounts by property or entity keep your records clean.
- Save everything for at least three years. The IRS generally has three years to audit your return. Some situations extend that to six. When in doubt, keep it.
The bottom line: organized property income analysis is not just good business practice. It is how you protect yourself from penalties and maximize your legitimate deductions.
My take: stop treating rental income like a single number
I have worked with a lot of property owners over the years, and the single most common mistake I see is treating rental income as one number. A property brings in “X dollars a month” and that is the extent of the analysis. But that single number is like reading only the final score of a baseball game. You know who won, but you have no idea why.
In my experience, the owners who grow their portfolios most confidently are the ones who know exactly where every dollar comes from. They can tell you that their pet fee policy generates $2,400 a year per property, or that their utility reimbursement structure is underpriced relative to actual costs. That kind of granular awareness comes entirely from detailed revenue tracking.
I have also seen the chaos that follows when owners try to reconcile owner accounts after months of sloppy categorization. It is not a fun conversation, and it usually costs money to fix. Getting the right software early, even before you think you need it, saves an enormous amount of pain later. Think of revenue tracking not as an accounting chore but as an active part of your investment management strategy. The data you collect today is the foundation for every smart decision you make tomorrow.
— Philipp
Let Home24seven handle the numbers for you
Keeping up with income categorization, owner statements, and tax-ready reports is a real time commitment. If you are managing a vacation rental in Cape Coral and spending your weekends reconciling spreadsheets instead of enjoying the Florida sun, something has gone sideways.
At Home24seven, we have been managing short-term and vacation rentals since 2017, and financial transparency is built into everything we do. Our remote rental management service gives you detailed owner statements, clear income reporting by property, and the kind of organized records your accountant will actually appreciate. We track every revenue stream, from nightly rates to cleaning fees, so nothing falls through the cracks. If you are ready to stop wrestling with the books and start seeing real clarity on your rental income, check out our full-service management options and see what stress-free ownership actually looks like.
FAQ
What is property revenue tracking?
Property revenue tracking is the process of recording, categorizing, and allocating all income a rental property generates, including base rent, fees, and reimbursements, by property, unit, and income type to support accurate reporting and investment decisions.
What income should I track beyond monthly rent?
Beyond base rent, you should track late fees, pet fees, parking charges, utility reimbursements, move-in fees, storage fees, and any forfeited security deposits, since each represents a distinct revenue stream with its own tax and performance implications.
What is the difference between cash and accrual accounting for rentals?
Cash basis records income when you receive payment, while accrual basis records it when it is earned. Most individual landlords use cash basis, but the choice affects how income appears on your tax return and in your monthly reports.
How does a chart of accounts help with rental income?
A chart of accounts organizes your income into detailed sub-categories by property and income type, which makes financial reports more useful, simplifies Schedule E tax filing, and prevents the costly misclassification errors that come from lumping everything into one broad income account.
What records does the IRS require for rental income?
The IRS requires you to report all rental income and maintain documentation including lease agreements, payment receipts, and fee records. These good records protect you from audit penalties and support your deductions on Schedule E.

