

TL;DR:
- Rental yield measures the annual income from a property as a percentage of its value, informing investment potential.
- Understanding both gross and net yields helps investors evaluate true profitability after expenses and market factors.
If you’ve ever looked at a rental property and wondered whether it’s actually worth buying, rental yield is the number that cuts through the noise. It’s the percentage return you earn from rental income relative to what you paid for the property. Simple enough on the surface, right? But a lot of investors either misread it, miscalculate it, or treat it as the whole story when it’s really just the opening chapter. This guide breaks down what rental yield means, how to calculate it properly, what moves the needle on it, and how to use it without getting burned.
Table of Contents
- Key Takeaways
- What rental yield actually means
- How to calculate rental yield
- What affects rental yield
- Rental yield vs. capital growth
- Practical tips for maximizing rental yield
- My honest take on rental yield
- How Home24seven helps you put yield to work
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Gross vs. net yield | Gross yield ignores expenses; net yield is the number that actually reflects your real return. |
| The healthy yield range | A gross yield between 5% and 8% is generally considered strong for residential properties. |
| Yield is a filter, not a verdict | Use rental yield to screen properties quickly, but always factor in taxes, financing, and market appreciation before buying. |
| Expenses eat into returns | Typical landlord costs reduce gross yield by 2 to 3 percentage points when calculating net yield. |
| Yield vs. growth trade-off | High-yield properties often sit in slower-growth markets, so balancing income now against appreciation later is a strategic call. |
What rental yield actually means
Rental yield is the annual income a property generates expressed as a percentage of its value. Think of it as the property world’s version of a dividend yield on a stock. It tells you how hard your money is working each year in the form of rent collected.
There are two versions you need to know: gross rental yield and net rental yield. Gross is the simpler calculation. It looks only at rental income versus purchase price. Net goes deeper by stripping out all the real-world costs of owning and operating the property.
Here’s why both matter:
- Gross yield gives you a fast, top-level snapshot for comparing properties side by side. Great for initial screening.
- Net yield shows what you actually keep after paying for management, insurance, maintenance, vacancies, and taxes. This is the real deal.
- Rental yield vs property value is the core relationship: when property prices rise without matching rent increases, your yield compresses. When rents rise faster than prices, yield expands.
- Yield reflects annual income potential, not capital growth, which is a separate metric entirely.
Understanding both gross and net yield is the foundation of understanding rental yield as a practical investment tool rather than just a marketing number thrown around at open houses.
How to calculate rental yield
Here’s where things get concrete. The rental yield formula is not complicated, but getting it right requires a bit of discipline.
Calculating gross rental yield
- Multiply your monthly rent by 12 to get annual rental income.
- Divide that annual income by the property’s purchase price (or current market value).
- Multiply by 100 to get your percentage.
Gross Rental Yield = (Annual Rent ÷ Property Value) × 100
So if a property costs $300,000 and rents for $2,000 per month, your gross yield is ($24,000 ÷ $300,000) × 100 = 8%. That looks great on paper.
Calculating net rental yield
Net yield takes that same formula and subtracts your annual operating expenses from the rental income before dividing. Operating costs typically include:
- Vacancy losses (an empty property still costs you money)
- Property taxes and insurance
- Maintenance and repairs
- Property management fees
- HOA fees where applicable
Net Rental Yield = ((Annual Rent − Annual Expenses) ÷ Property Value) × 100
| Scenario | Gross Yield | Annual Expenses | Net Yield |
|---|---|---|---|
| $300K property, $2,000/month rent | 8.0% | $6,000 | 6.0% |
| $400K property, $2,200/month rent | 6.6% | $7,500 | 4.6% |
| $500K property, $2,500/month rent | 6.0% | $9,000 | 3.6% |
You can see how quickly costs chip away at those headline numbers. A property advertising an 8% gross yield might realistically deliver closer to 5% or 6% net once you account for the real costs of ownership.
Pro Tip: When evaluating a short-term vacation rental, factor in seasonal vacancy rates and higher cleaning or management fees. These costs can be significantly steeper than long-term rental expenses, so your net yield calculation needs to reflect that reality.
What affects rental yield
Rental yield does not live in a vacuum. A stack of variables push it up or drag it down, and understanding them saves you from buying a “high-yield” property that underperforms once reality sets in.
Location and market dynamics carry the heaviest weight. A gross yield above 6% signals strength in many UK markets, while Australian suburbs like Treeby sit closer to 3.6% gross. In the US, residential yields average 3% to 5% after costs. Cape Coral, Florida, with its tourism-driven short-term rental demand, often punches above national averages for investors who manage their properties well.
Property type and condition matter more than most beginners expect. A well-maintained property commands higher rent and attracts longer stays. Deferred maintenance kills yields faster than you’d think because one bad repair season can wipe out months of profit.
Vacancy rates are the silent yield killer. A property sitting empty for six weeks a year effectively reduces your annual income by over 11%. Every vacant night is income you can never recover.
Operating expenses and management costs vary widely depending on how hands-on you are. Self-managing cuts costs but demands your time. Professional management adds fees but can boost rental income by optimizing pricing, reducing vacancies, and maintaining the property to a higher standard.
Currency risk for international investors is a factor that rarely makes it into beginner guides. If you’re investing across borders, currency depreciation can erode what looks like a strong nominal yield. Indian rupee devaluation at 3 to 4% annually against the US dollar, for example, meaningfully narrows the yield gap between markets that seem far apart on paper.
Rental yield vs. capital growth
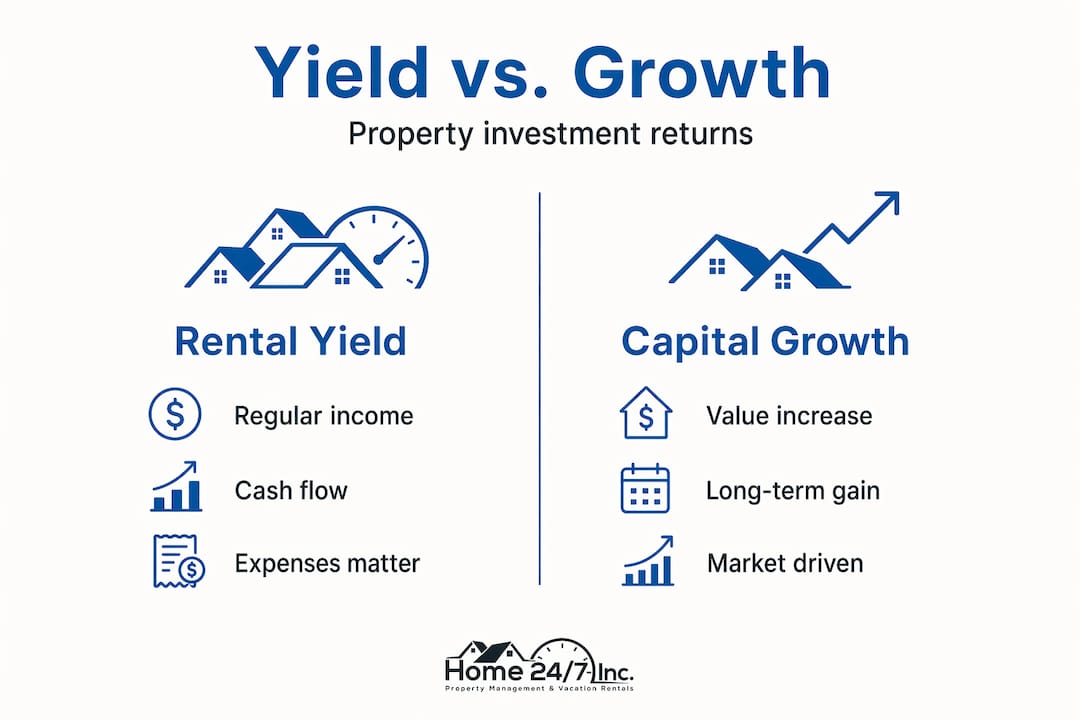
Yield and capital growth are the two engines of property investment returns. You rarely get both firing at full throttle simultaneously, which is why understanding the trade-off matters so much.
| Metric | What it measures | Best for |
|---|---|---|
| Rental yield | Annual income as % of property value | Cash flow investors, retirees, income seekers |
| Capital growth | Appreciation in property value over time | Long-term wealth builders, equity investors |
| Cash flow | Net income after all debt service and costs | Day-to-day financial sustainability |
Rental yield offers predictable income linked to inflation and tends to hold up better during economic downturns than capital growth does. Capital growth, by contrast, builds long-term wealth but depends heavily on market cycles. A property in a booming city might grow 15% in value over two years while yielding only 3% annually. A vacation rental in a stable beach market might yield 8% while appreciating more modestly.
“Yield tends to be more recession-proof, while growth offers higher liquidity but depends on market cycles.” — Titan Wealth International
The smartest investors think about both metrics together rather than chasing one at the expense of the other. A short-term rental in Cape Coral can potentially deliver meaningful yield while benefiting from Florida’s long-term property appreciation trend. That’s the sweet spot.
One more thing worth knowing: rental property cash flow benefits from a depreciation tax shield that stocks and REITs simply do not offer. That structural tax advantage makes direct real estate more attractive on an after-tax basis than the raw yield numbers might suggest.
Practical tips for maximizing rental yield
Getting a solid yield does not happen by accident. It takes deliberate strategy and honest expense tracking.
- Price your rental accurately. Underpricing leaves money on the table; overpricing drives up vacancy. Optimizing short-term rental pricing with dynamic tools based on demand and seasonality is one of the fastest levers you have.
- Track every expense meticulously. Investors who eyeball costs instead of recording them consistently overestimate their actual yield. Use real numbers.
- Consider ancillary income streams. UK landlords adding garden cabins or studios to their properties have boosted net yields by 12% to 38%. The same principle applies to pool houses, garage conversions, or adding amenities that justify premium nightly rates.
- Do not overpay for the property. This sounds obvious, but purchase price is the denominator in your yield formula. Paying $50,000 above market to win a bidding war directly compresses your yield before the first tenant walks in.
- Treat yield as a quick screening metric, not the final answer. Tax implications, financing costs, and local market trends all need separate analysis before you write a check.
Pro Tip: Professional property management can feel like a yield-reducer because of the fees, but a skilled manager who cuts vacancy rates by even 10% and commands 5% higher nightly rates often delivers a higher net yield than the self-managing landlord who thought they were saving money.
My honest take on rental yield
I’ve seen plenty of investors walk into properties armed with nothing but a gross yield figure and a lot of confidence. And most of them got humbled pretty quickly.
The number that worries me most is gross yield presented as if it were net yield. A Cape Coral property advertising 9% gross might net 5.5% after management fees, insurance, cleaning between guests, and a couple of slow months in shoulder season. That’s still a solid return, but it’s a completely different conversation from 9%.
What I’ve learned over years of working with vacation rental properties is that the investors who do best are the ones who separate yield from appreciation in their thinking and then deliberately choose which one they’re optimizing for. Chasing the highest advertised yield without understanding the local market, expense structure, or vacancy patterns is a recipe for disappointment.
Rental yield is genuinely useful. It’s a fast, standardized way to compare properties across markets. But use it as a filter, not a verdict. The real work is what comes after the yield calculation: understanding the market, knowing your costs, and managing the asset well.
The investors I respect most treat their rental properties like businesses. They know their numbers cold, they optimize expenses without sacrificing quality, and they think in terms of total return rather than just the headline yield figure.
— Philipp
How Home24seven helps you put yield to work
Getting your rental yield right is one thing. Actually achieving it month after month is where things get real.
At Home24seven, we’ve been helping Cape Coral property owners maximize rental revenue since 2017. We handle the things that quietly drag down net yield: vacancy-reducing marketing, dynamic pricing, guest communications, cleaning between stays, and maintenance coordination. Our full-service property management approach is built around one goal: putting more money in your pocket while taking the headaches off your plate. If you’re ready to stop guessing at your yield and start knowing it, our remote rental management services make it possible from anywhere in the world. Let’s talk numbers.
FAQ
What is rental yield in simple terms?
Rental yield is the annual rental income you earn from a property expressed as a percentage of its purchase price or current value. It tells you how efficiently your investment is generating income.
What is a good rental yield for a residential property?
A gross yield between 5% and 8% is generally considered healthy for residential properties, though what qualifies as “good” depends heavily on the local market and your investment goals.
How is net rental yield different from gross?
Gross yield calculates income before expenses; net yield subtracts all operating costs including management fees, insurance, repairs, and vacancy losses. Costs typically reduce gross yield by 2 to 3 points to arrive at net yield.
Can rental yield tell me everything I need to know about a property investment?
No. Rental yield is a quick screening tool, not a complete investment analysis. You still need to account for financing, taxes, capital appreciation potential, and local market conditions before making a purchase decision.
Does property management help or hurt rental yield?
Quality property management typically improves net yield over time by reducing vacancies, optimizing pricing, and protecting the asset through proper maintenance, even after accounting for management fees.

